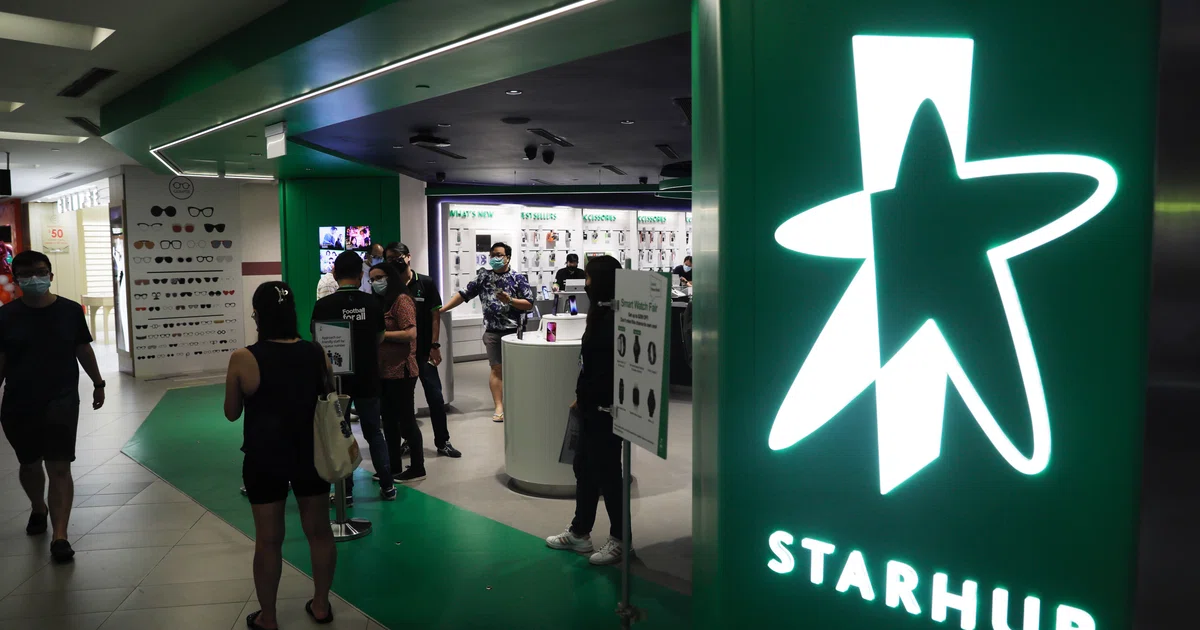
Enterprise segment picking up consumer slack at StarHub; telco remains open to industry consolidation: Maybank
StarHub’s cybersecurity arm, Ensign, continues to deliver double-digit revenue growth. This comes as the telco’s consumer segment reels from intense competition and customer downtrading, said Maybank Research.
In a report released on Monday (Jul 7), analyst Hussaini Saifee noted that other than Ensign’s revenue growth, key wins for the enterprise unit – such as the JTC Punggol Digital District – reflect execution strength and are viewed as replicable in other markets.
However, Saifee noted that the enterprise segment’s structurally lower margins, as compared to the consumer segment, could weigh on group profitability.
StarHub management expects the consumer shift from premium services to value-plans to persist through 2027 and 2028, the anaylst noted. “Management reiterated that Singapore’s mobile and fixed broadband markets remain intensely competitive, driven by four mobile network operators and seven mobile virtual network operators.”
StarHub has gained consumer subscriber share across all three market segments, the premium, digital, and value markets. Saifee noted that the telco has widened its market share gap against M1 to six percentage points.
“StarHub is open to industry consolidation, but it says there is no timeline or details.”
BT in your inbox
Start and end each day with the latest news stories and analyses delivered straight to your inbox.
There was heightened speculation last year about a possible merger between StarHub and M1. There was also talk that if there was a deal, it would be closed before June 2025, so as to avoid the payment of the 700MHz spectrum fees.
However, Saifee believes that StarHub has likely already taken delivery of the 700MHz spectrum.
It is not clear if StarHub has taken all its allocated lots.
The 700MHz spectrum is a frequency of radio waves used to carry mobile broadband signals.
StarHub’s management flagged its healthy balance sheet, which has a net leverage of 1.3 times and about S$600 million in cash, as supportive of acquisitive merger and acquisition, said the analyst.
“That said, we expect cash to decline following the 700MHz spectrum payment.”
Maybank Research maintained its target price for StarHub at S$1.10, with a recommendation of “hold”.
Shares of StarHub were trading 0.9 per cent lower at S$1.17, as at 12pm on Tuesday.
Originally published by businesstimes.com.sg. Syndicated material does not necessarily reflect the views of Grazia British.
More Culture

Don’t Pull Out of Germany
Merz’s stupidity is no excuse for a stupid response. Source link
Step inside the gorgeous, futuristic offices of Vast, the startup designing the next-gen space station
A tall baobab tree greets people inside the Long Beach, California, headquarters of Vast, an aerospace company that is building the space station of the future. It’s planted beneath a…
5 ways high-performing teams stay calm when everything’s on fire
When markets swing, plans break, inboxes explode, and everyone starts saying the situation is “unprecedented” again, most teams do what humans have always done under pressure: they grip…

Confused Trump Openly Admits Plot to Rig Midterms as Polls Turn Brutal
Last week, the Supreme Court gutted protections against racial gerrymandering, and Donald Trump is already urging Republicans to seize on it. Trump unleashed a Truth Social rant on Monday…