Refi boomlet starts in housing market as mortgage rates slide from highs
Want more housing market stories from Lance Lambert’s ResiClub in your inbox? Subscribe to the ResiClub newsletter.
Heading into the fall last year, the average 30-year fixed mortgage rate slipped to a low of 6.07% by September 17, 2024 as the market reacted to weaker than expected labor market data. At that point, there was a noticeable upswing in refinances as some 2022–2024 borrowers took the opportunity to get payment relief.
However, it was short-lived and quickly fizzled out once labor market data tightened a bit and mortgage rates popped back up.
Fast-forward to September 2025, and we’re once again seeing a mini “refi boomlet.”
Similar to early last fall, the average 30-year fixed mortgage rate has fallen a bit heading into September—with the average 30-year fixed mortgage rate hitting a calendar year low of 6.26% last week, according to Freddie Mac’s weekly reading.
With the average 30-year fixed mortgage rate sitting well below 2025’s calendar-year high of 7.04%, some recent borrowers are taking the opportunity to refinance and gain some payment relief.
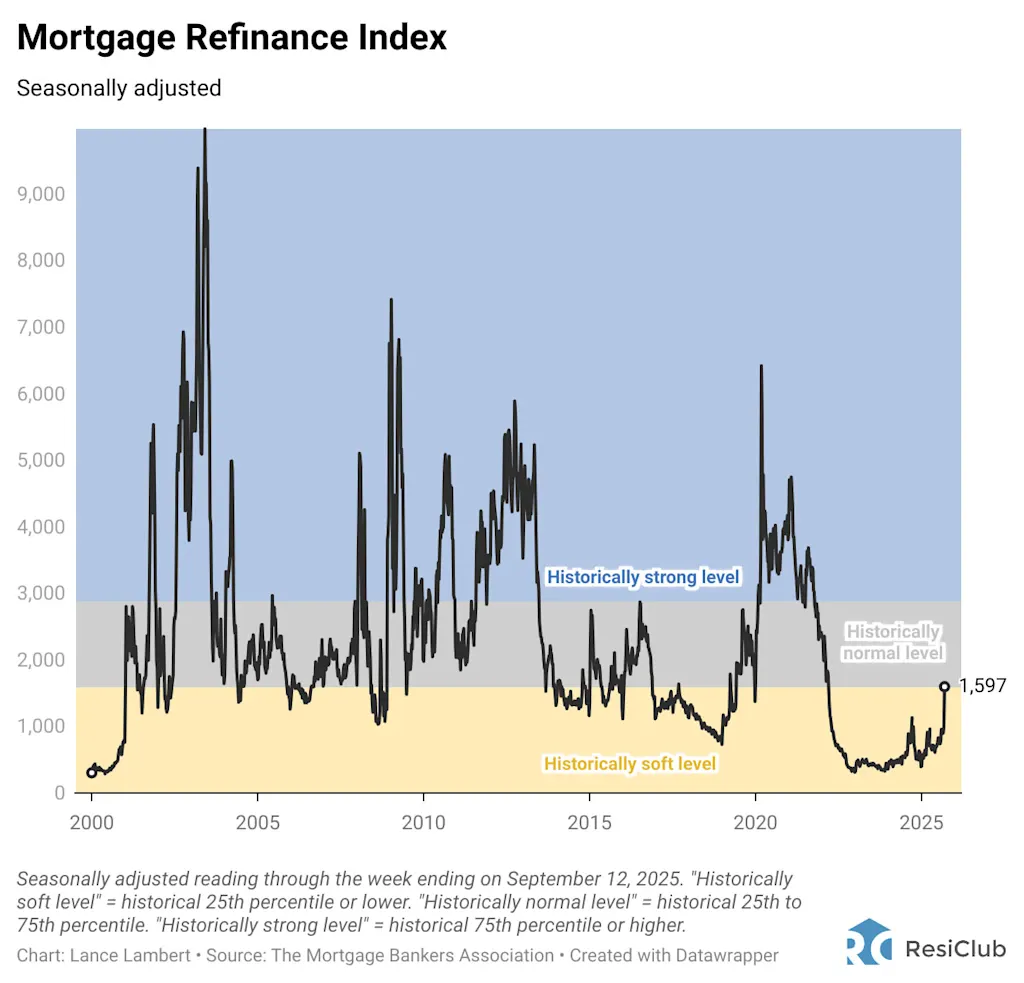
The Mortgage Refinance Index reading for the second week of September, by year:
- September 14, 2018: 917
- September 13, 2019: 2,274
- September 11, 2020: 3,289
- September 10, 2021: 3,186
- September 9, 2022: 533
- September 8, 2023: 367
- September 13, 2024: 941
- September 12, 2025: 1,597
If you look closely at the chart above, you’ll notice that last year’s peak weekly reading for the Mortgage Refinance Index (1,133 on the week ending September 21, 2024) is well below the reading we just saw for the week ending September 12, 2025—even though mortgage rates last September dipped slightly lower than they did this September.
The reason this September’s refi boomlet is likely bigger than last year’s is that many borrowers who held out for a larger rate drop last fall were burned when mortgage rates jumped back up late in 2024. So when the opportunity for payment relief came around this year, many jumped on it.
You may have noticed thatResiClub calls this a “refi boomlet” rather than a “refi boom.”
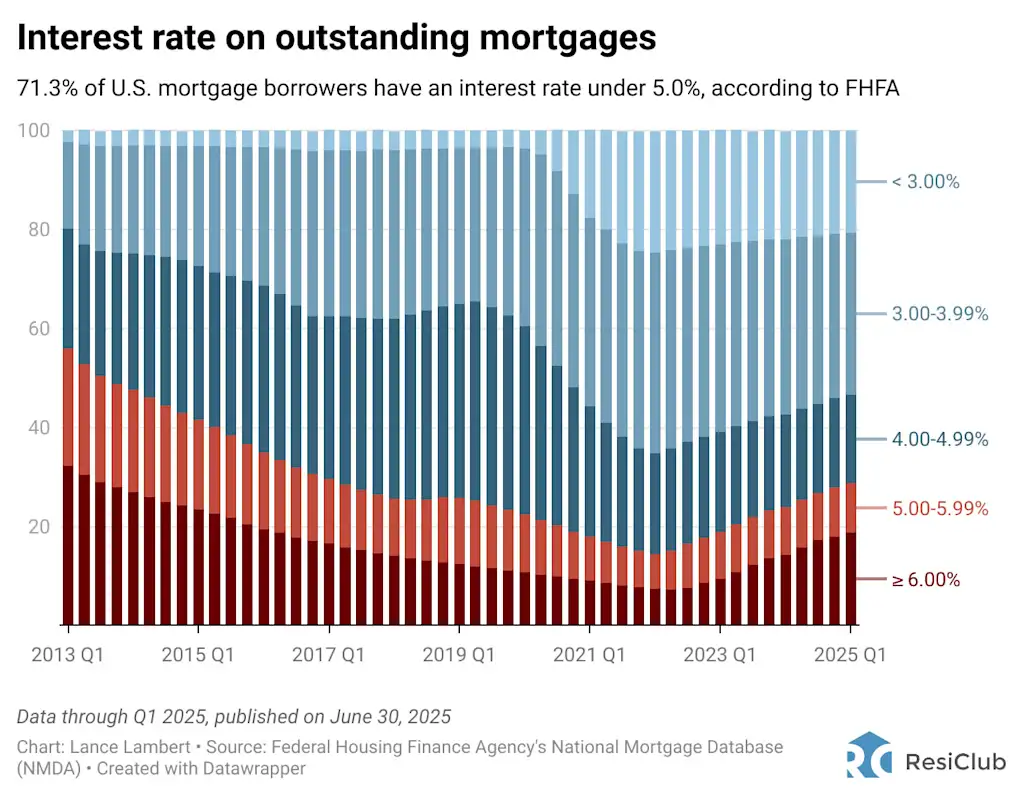
We use the term boomlet because there’s a ceiling on how big this refinance pop can get—and how long it can last—without a much more substantial drop in mortgage rates. After all, according to the latest FHFA data, 71.3% of U.S. mortgage borrowers still hold an interest rate below 5.0%.
How far would mortgage rates need to fall to spur a real refi boom? Read this ResiClub article.
Originally published by fastcompany.com. Syndicated material does not necessarily reflect the views of Grazia British.
More Culture

Don’t Pull Out of Germany
Merz’s stupidity is no excuse for a stupid response. Source link
Step inside the gorgeous, futuristic offices of Vast, the startup designing the next-gen space station
A tall baobab tree greets people inside the Long Beach, California, headquarters of Vast, an aerospace company that is building the space station of the future. It’s planted beneath a…
5 ways high-performing teams stay calm when everything’s on fire
When markets swing, plans break, inboxes explode, and everyone starts saying the situation is “unprecedented” again, most teams do what humans have always done under pressure: they grip…

Confused Trump Openly Admits Plot to Rig Midterms as Polls Turn Brutal
Last week, the Supreme Court gutted protections against racial gerrymandering, and Donald Trump is already urging Republicans to seize on it. Trump unleashed a Truth Social rant on Monday…